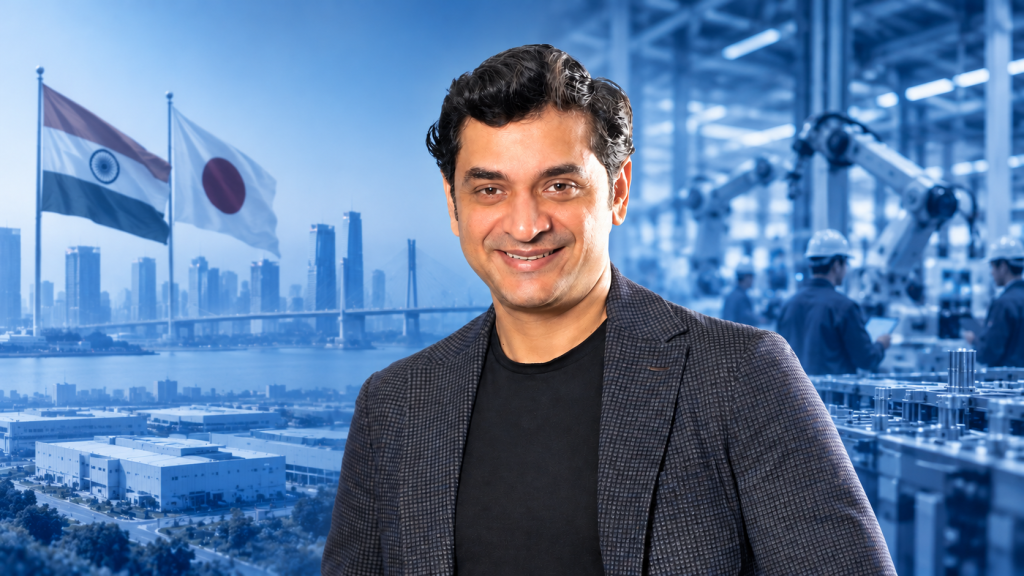
Akhilesh Ayer joined Cactus Communications (CACTUS) as CEO in September 2024. In this interview, he discusses CACTUS’s deep roots in Japan and why India’s scale, technology capabilities, and talent ecosystem create a compelling opportunity for Japanese companies. Akhilesh, who developed strategy for a business process management and digital transformation company before joining CACTUS, discusses how Japanese businesses can build effective GCCs in India, choose the right locations and operating models, bridge cultural and regulatory differences, and evolve their GCCs beyond cost efficiency into centres for innovation, R&D and global capability.
How central is Japan to CACTUS’s identity and business today?
Many people may not know that while CACTUS is headquartered in India, it pretty much started its business in Japan. It expanded its revenue pools and business first in Japan before expanding to other geographies. Japan has been the largest service centre for pretty much all of CACTUS’s existence and continues to be the centre of its strategy and vision as we look to the next 5-10 years. Japan has been at the forefront of science and technology and research. And CACTUS has been central to enabling or working with Japanese researchers to ensure that their science gets published, recognized, and disseminated across the globe.
There is a huge potential for Japanese companies and Japan’s economy to exploit the benefits of global developments, talent pool, AI, and more. CACTUS is uniquely positioned as its business model evolves to helping Japanese corporations leverage the best of global supply chains and talent pools to expand its presence globally and take advantage of economies of scale.
Being a company headquartered in India and operating globally, what specific features of India’s talent and knowledge ecosystem make it uniquely positioned to serve the Japanese corporate clients?
India, over the last 23-30 years, has made huge strides in technology and talent-based growth. It is pretty much the IT backbone of the world. Not only Indian companies but also many foreign companies leverage the Indian talent and knowledge ecosystem. Many respected Japanese brands have a huge presence in India.
At many points in time for a large part of CACTUS’s existence, almost 50 employees from Japan were based out of India. This was the largest talent pool of Japanese citizens based out of India across any industry, any company.
CACTUS’s technology and knowledge backbone is very strong. Not only can we support the talent and knowledge ecosystem of India. But since we see ourselves partly as a Japanese company, we can bridge the cultural and regulatory gaps and be seen as a trusted company.
CACTUS has a dedicated Japan subsidiary (Cactus Communications KK) with a Japanese representative director. How do you manage the relationship between the India headquarters and the Japan subsidiary?
Japan is our largest market. A lot of our business, not only in Japan but all of East Asia, is managed out of Japan. The India office serves as a strategy facilitator and an operations backbone to Japan. The Japan team works on strategy and understands customer needs, regulations, and trends, and collaborates with the Indian team to build services for the Japanese market. Also, the Japan team is able to leverage the scale of India in terms of manpower, technology, and knowledge systems. This model has worked extremely well for us for over 20 years. This has allowed us to translate customer needs seamlessly and much faster.
What lessons from this model apply to Japanese companies trying to run India GCCs from Tokyo?
Japan and India enjoy long-term and strong relationships at all levels. There are some cultural similarities, and people should be mindful of them. Also, Japan has started making more investments in India, in its infrastructure and other sectors. And India is looking at Japan as a potential market, which was not the case before.
India is the largest, most populous country in the world, with a growing middle-class population. Today it is about the 4th largest economy and poised to be the third largest soon.
All trends suggest that the market is only going to increase. There is a history of large Japanese companies with a strong presence in India, and there is no reason other Japanese companies should not find a home here.
There are a few things Japanese companies should bear in mind. One, it’s important to understand the cultural nuances of India. Two, you need to understand the legal and regulatory working. To bridge this gap, you need to work with people you can trust or can relate to. Find a partner that has worked in India and Japan for long enough, and who understands how Japanese organisations and corporations think and how India reacts to it.
GCCs are increasingly being judged not just as cost centres but as innovation engines. In your view, which Indian cities beyond Bengaluru are genuinely emerging as credible GCC hubs for Japanese companies in advanced R&D or AI? What infrastructure gaps still exist?
I agree that GCCs are increasingly being seen as either innovation engines or capability centers. Cost arbitrage and control of operations are the biggest reasons why companies set up GCCs. But increasingly, a lot of companies are running innovation experiments and transferring innovation budgets to the GCCs.
Bengaluru definitely has the largest number of GCCs and a very large talent pool, but sometimes managing talent there can be tough because of mobility of people across companies.
There are other pockets of excellence in India. Hyderabad is very good for life sciences and pharma because it’s home to many companies other than technology, AI, and R&D. Chennai and Pune are very good for manufacturing-based R&D as well as technology centers. Mumbai is the financial capital of India and therefore home to all financial institutions. The state government is coming up with a large GCC city near Mumbai where there will be a lot of financial incentives for people to set up. You can always find talent in Mumbai. The National Capital Region (NCR) near Delhi is also a big centre for back offices and operational processes.
The government has made strides in some areas, like airport connectivity, office spaces, and centres in clusters. So, you’ll find people of similar talent groups clustered around hubs. The cost of data, I think, is one of the lowest in the world in India. The telephony infrastructure is much better. And there is supporting infrastructure that is made available.
Are Japanese companies in India using acquisitions strategically to build GCC capabilities or are they mostly greenfield? What would your M&A advice be to a Japanese firm wanting to quickly establish a GCC in India?
This is not restricted to Japanese companies. M&A is a hit or miss. It is always risky and more often than not acquisitions fail for cultural reasons. When you’re doing an M&A-led strategy, you have to be very mindful of the cultural sensitivity of the two organizations. A greenfield approach can be expensive, sometimes risky, and the gestation period is long. And therefore, many people look at brownfield opportunities, a partner-led growth. Your partner helps you learn the ropes of the trade and understand market dynamics, consumer preferences, regulations, ways of operating, etc. before you can think of branching out independently.
It all boils down to your strategy. If you know the market well, then it’s okay to do an M&A or a greenfield. Even with a brownfield approach, there are multiple options where you work through an intermediary like CACTUS that can carry out part of the initial work before you take over.
CACTUS serves customers in 190+ countries through a remote-first model. How has this changed your thinking about what a “centre” in GCC actually means? Does the physical concentration of talent in a city still matter, or are we moving to distributed GCC models?
Historically GCCs were set up in one building where many of the employees were housed together. Then you started seeing a cluster of buildings in cities like Bengaluru, Hyderabad, Pune, Chennai, or NCR. First, talent was concentrated in a small area and the talent force was largely made up of young people. They would move to these hubs from tier 2 cities. Companies had to offer transport between offices and homes and this is how other infrastructure came into play. This is how the GCC model evolved.
After COVID, things have changed a lot. Many of these employees who had moved from tier 2 and 3 cities had to go back to their hometowns and work from there. Technology had to evolve to enable that. Security protocols had to change, and bandwidth had to be adjusted. Many platforms moved to the cloud to allow this. Now many of the GCCs work in a hybrid structure, where they have a central location that houses many critical functions, but many other functions operate in a distributed manner. And companies don’t mind the hybrid structure. It provides them control where needed. But they can allow the workforce to manage their work-life balance and attract talent from different parts of the country.
The only industries where having central hubs are non-negotiable is where there are strict regulations, where personal data is involved, security is of paramount concern, or there are end-industry regulations that prevent data and workflows/systems to move out of one place. In that case, it becomes difficult to operate in a remote model, but there are workarounds. Increasingly I see a lot more hybrid structures where a balance is struck by asking people to come to the office either by function or on certain days and creating a hub-and-spoke model.
JETRO surveys show that 81.5% of Japanese firms plan to expand in India — the highest globally. Yet many Japanese companies still manage India through regional Asia-Pacific headquarters in Singapore or Hong Kong rather than directly. What does this structural choice cost them in terms of GCC effectiveness?
There could be administrative reasons. Historically these locations have always been operational hubs for many markets or companies across the globe, both in the East and the West. Those were large financial markets, trade routes, or important shipment hubs.
There’s nothing wrong with this structure. The Indian economy used to be much smaller and a developing economy, and it was easier from a cultural, financial, and administrative perspective to have management control out of Singapore or Hong Kong.
Things have changed drastically now. India has emerged as one of the largest economies in the world. The market is large. The complexity of managing India is also higher because of the market size. The Indian ecosystem is very diverse. And, therefore, if you need to establish India as a market, a local India-based management structure is necessary even if you have a Singapore or Hong Kong structure.
If you look at successful large Japanese companies like Toyota, Honda, or Hitachi, all of them now have a strong presence in India. You’ve even got some large companies operating GCCs in India, which directly deal with the headquarters in Japan. This is because of the market potential India offers.
Japanese companies are still slow to get on the GCC bandwagon even though there is a history of Western countries setting up BPOs or operational centres in India. Why do you think this is? And what should Japanese companies do to set up and expand faster in India like other countries have done?
Western countries find it easy to set up in India because India has the largest number of English speakers in the world – more than the US and UK. This was an advantage in the service sector. In the manufacturing sector, China took the lead in the late ‘70s and ‘80s. But many companies now are moving their manufacturing to India, even if partly. Look at Apple for example.
Japanese companies may be hesitant because of the fear of the unknown. Sometimes you just don’t know what the market looks like and that increases the risk perception of doing it.
There is high intent of entering India, and it is important to engage and test the waters. For this, it’s important to do two things: First, find a trusted partner whom you can rely on and who understands both Japan and India, someone who can simplify and explain how things need to be done. Second, look at other Japanese companies that are entering or have entered India. The consultant-partner can facilitate that as well by creating a list of references.
The earlier they do this, the easier it will be for them to formulate a strategy. Otherwise it’s a missed opportunity. You enter the market late and lose out on sales growth, but you also miss out on efficiencies, innovation, and cost benefits.
India is home to over 50% of the global GCCs. What is the best way for Japanese companies to extract value out of GCCs in India?
Companies need to engage with the GCC ecosystem far more effectively. But as and when they set up or start operationalizing a GCC, they need to provide a lot of orientation and exposure to the Japanese companies’ way of working. It is very important to orient and invest in training and orientation of the Japanese companies, products, and services, but also culture and operating model. Some companies do not do a good job here. They set up the GCC and hire teams, and start expecting results. You put in a lot of effort and get no results.
It’s important to understand people, culture, processes, and systems in both companies. Think of the way we communicate. In India, people do not say “no” very quickly. When they are on calls with people from other countries, they will nod their head to something being said. This usually means “I hear you.” But a person from another culture may misinterpret that as “I agree with you.” This creates an incorrect expectation. So it’s important to invest a little bit more upfront in cultural orientation, process orientation, practices, and product orientation.
How important a role does government policies play here? Do you find India’s government policies more business friendly compared to other countries?
The government of India has always shown an interest in growing the GCC space. There are industry bodies which advice the government on policy, incentives, talent training, etc., all aimed at promoting the GCC infrastructure. Some state governments are promoting tier 2 to tier 4 cities as hubs and offering incentives to set up GCCs there.
Deciding which country to set up in is a matter of strategy. Other countries also offer incentives, but most countries won’t offer you the scale or the talent you need. The Philippines, for example, serves as a hub for the US. The US has set up a lot of voice contact centres there. But if you are looking for technology or R&D talent, you’re not going to find it in the Philippines. Eastern Europe offers good engineering talent and its languages and time zone meet the needs of continental Europe. But it won’t offer scale.
Therefore, a good GCC strategy is to keep India as your main hub. And as you expand, you can look at some other places for specific needs and you know there will be incentives available.